
Patients paying out of pocket could face thousands of dollars a year for semaglutide treatment once repeat prescriptions, appointments, tests and changing discount terms are included.
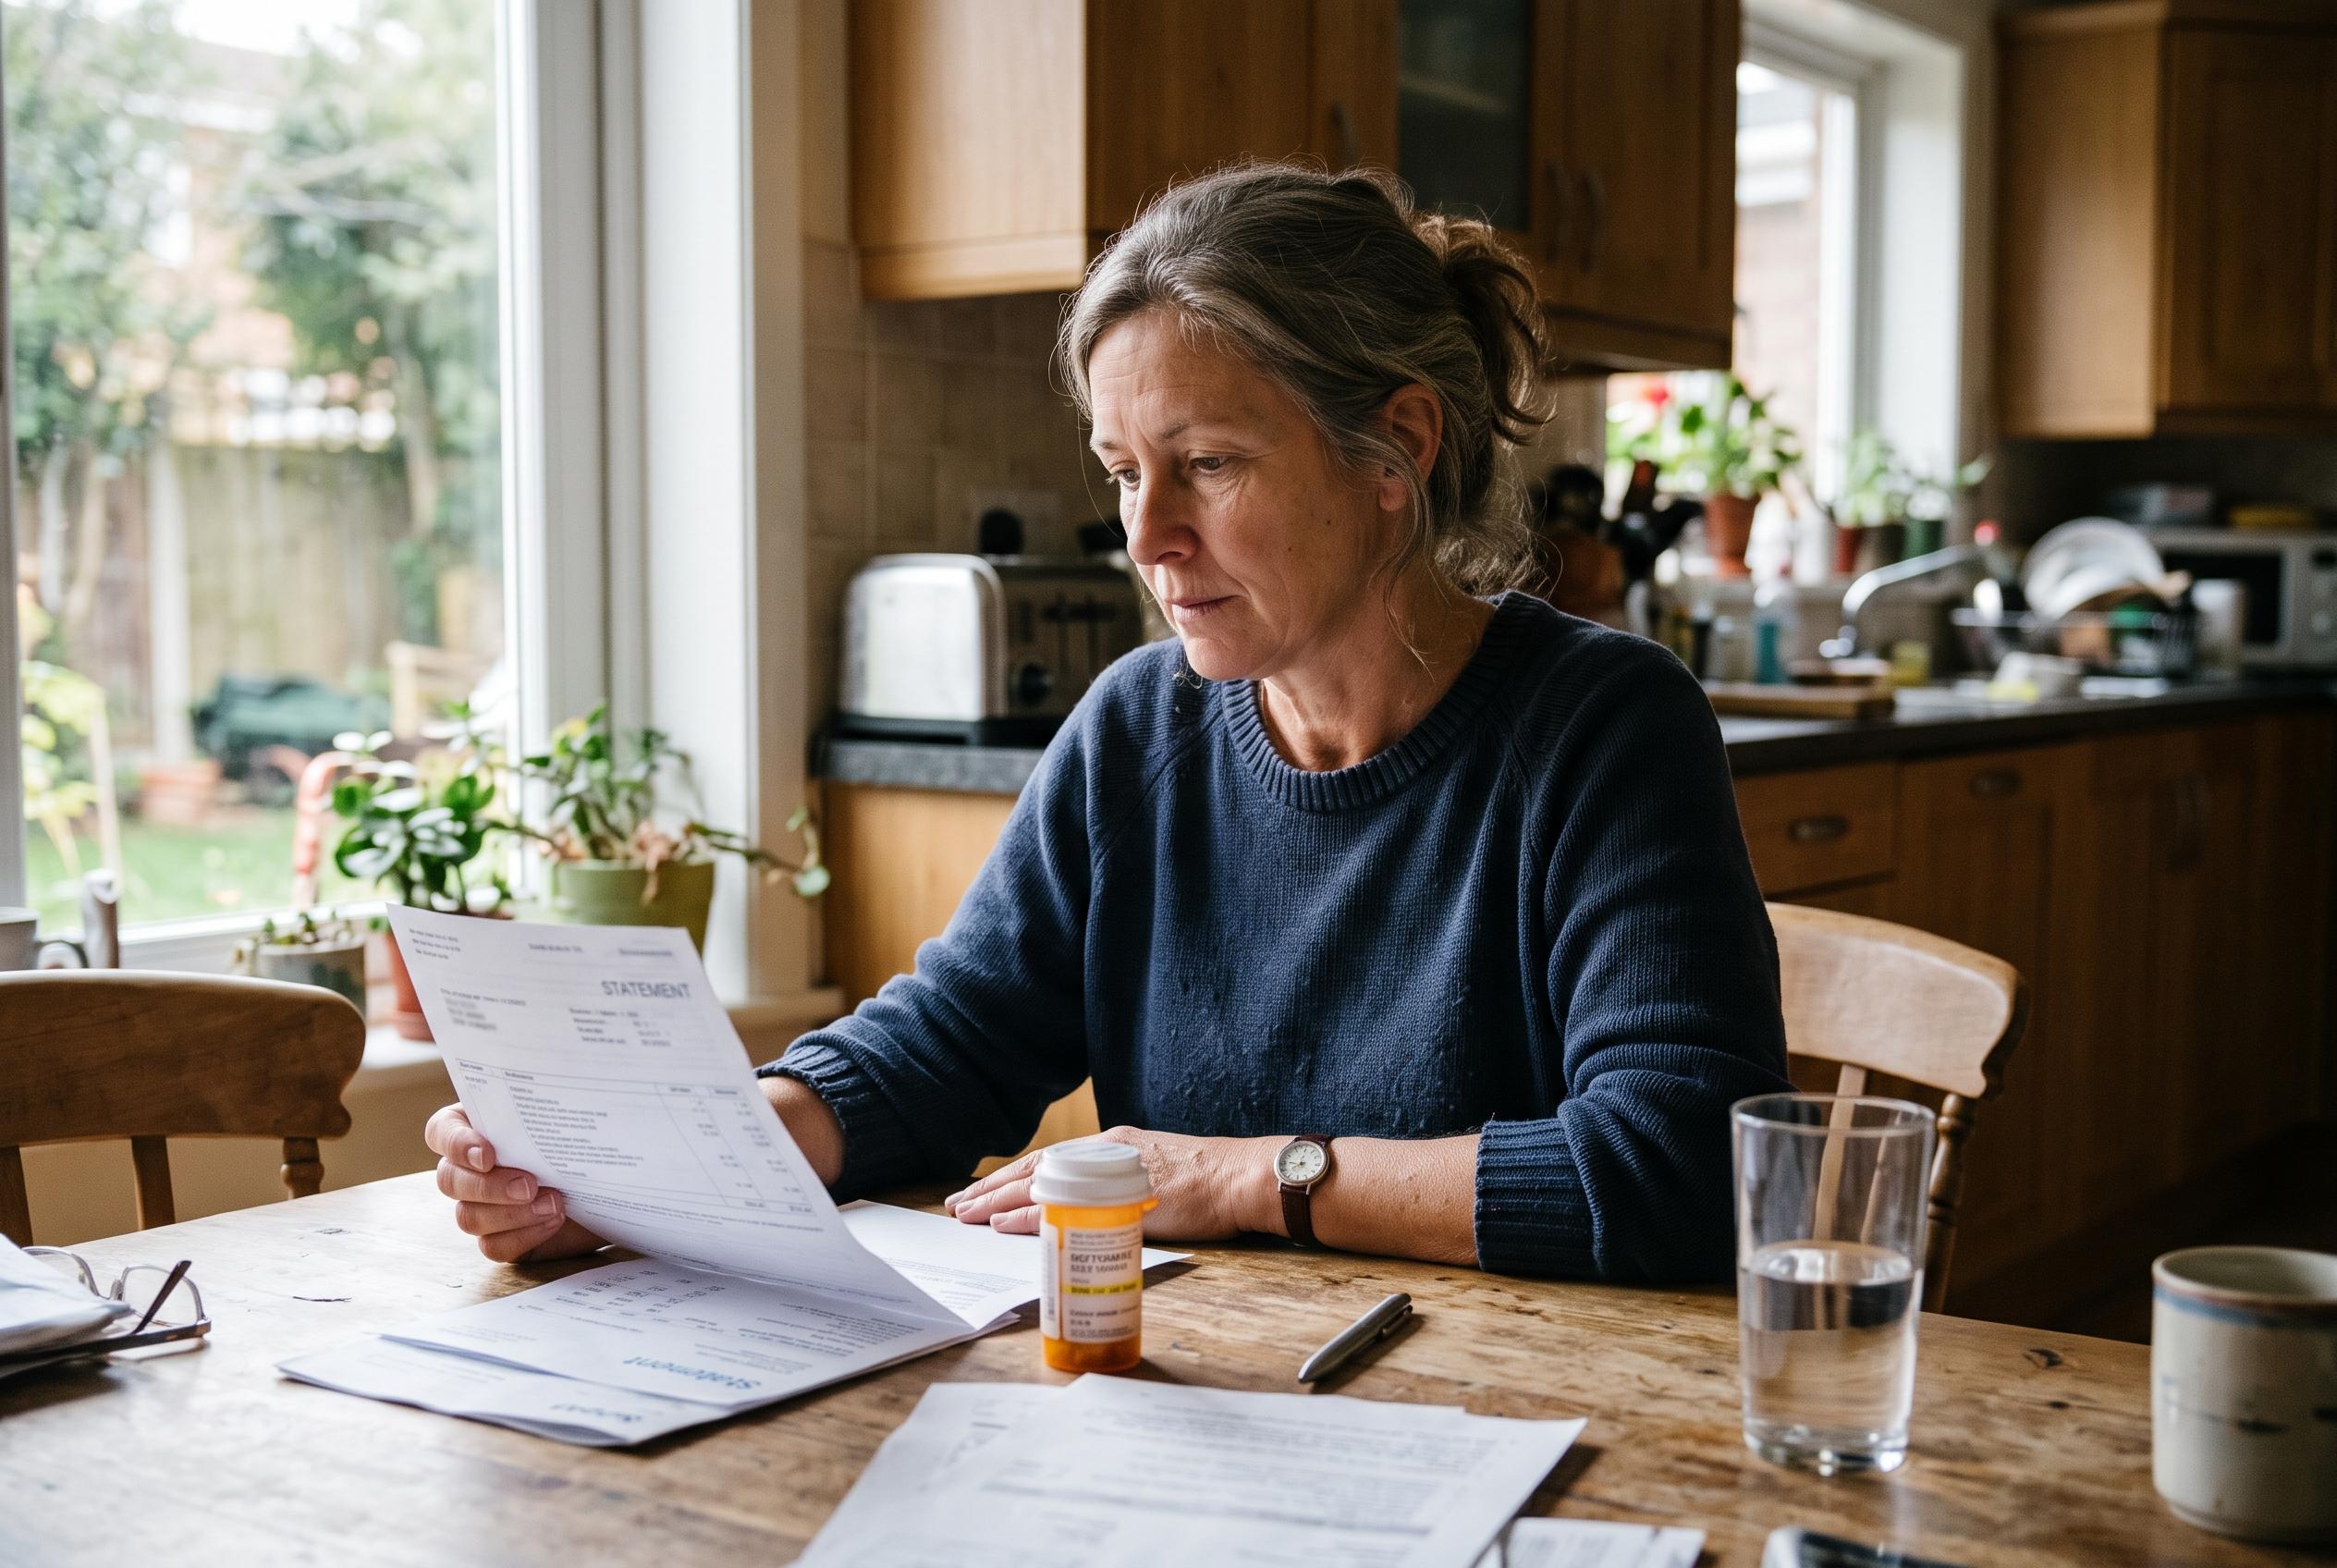
The first monthly quote for Ozempic or Wegovy can seem manageable, but the arithmetic changes quickly once a prescription is renewed month after month. For anyone paying out of pocket, the real question is not simply what the drug costs at the counter today, but what the full course of treatment may add up to over 12 months, including doctor visits, follow-up checks and any lab work that may be needed.
That longer view matters because monthly pricing can mask a very large annual bill. A prescription that appears affordable at $500 a month would total $6,000 over a year, while a $700 monthly charge would come to $8,400 before any related medical costs are counted. Actual prices vary by pharmacy, dose and available discounts, so the sensible approach is to budget around the amount a patient can truly obtain, not the headline figure in an advertisement.
Ozempic and Wegovy are often discussed together because both contain semaglutide, but they are not interchangeable from a medical or insurance perspective. Ozempic is approved for type 2 diabetes and, in some patients, certain cardiovascular and kidney-related uses. Wegovy is approved for chronic weight management and certain risk-reduction indications. Several medical comparison guides, including those from GLP Watchdog and GLP1.tools, stress that the approved use can affect both eligibility and the out-of-pocket bill.
That distinction is important before anyone assumes one brand is simply a cheaper version of the other. Coverage can depend on why the medicine is being prescribed, not just on the ingredient it contains. Drugs.com notes that insurers may cover Ozempic for approved diabetes-related uses, but patients should confirm the rules with their plan before starting treatment. Without that step, a patient may face an unexpected denial or miss a covered option entirely.
Prices can also shift over time, which means a decision based on one month’s quote may not hold for the full year. Novo Nordisk has said its U.S. list price for Wegovy and Ozempic will fall to $675 a month from January 1, 2027, although the company also said that change will not alter its separate direct-to-patient self-pay prices. That is a useful reminder that list prices, pharmacy cash prices and programme rates are not the same thing, and each may carry different terms.
The fine print matters as much as the headline figure. Some discount programmes have eligibility rules, dose restrictions or introductory pricing that changes later. A patient who starts with a lower monthly cost should ask what happens if the price rises, the dose changes or the offer expires. It is far better to calculate the full year using the terms that will actually apply than to discover too late that the budget only worked for the first few fills.
There is also a broader warning around cheaper-looking semaglutide offers. The FDA has cautioned that compounded medicines do not go through the same premarket review for safety, quality and effectiveness as approved drugs. That does not mean compounded products are never used appropriately, but it does mean a lower sticker price is not automatically the same as a like-for-like bargain.
Cash payers should also check whether they truly lack better options. Insurers may still cover one of these medicines under certain conditions, and manufacturer savings programmes can help some commercially insured patients. For Medicare beneficiaries, a temporary bridge programme has been introduced for eligible people seeking access to some GLP-1 medicines, including Wegovy, under specific rules through December 31, 2027. That makes comparison shopping essential: pharmacy price, insurance coverage and available assistance should all be checked before a patient commits to paying entirely out of pocket.
The main lesson is simple: the cost of treatment should be measured over time, not only at the first refill. A household that can manage one month’s bill may still find the annual total difficult to absorb once prescriptions, appointments and ordinary life are included. Before starting, patients should write down the likely medication price, expected medical costs and any discount conditions, then compare the total with the money available after necessities and savings. In a market where prices can change and coverage can be selective, a 12-month calculation is the best protection against an expensive surprise.
Disclaimer: This content is for informational purposes only and is not intended to be a substitute for professional medical judgment, advice, diagnosis, or treatment.